Why financial statements matter
Whether you are an investor evaluating stock potential, a business owner tracking monthly margins, or an analyst assessing credit risk, understanding the core financial reporting documents is essential. Types of Financial statements function as the universal scorecard of corporate performance, transforming raw accounting entries into structured, actionable intelligence.
Without standardized reporting, comparing companies across industries or evaluating long-term stability would be impossible. Regulatory bodies like the U.S. Securities and Exchange Commission (SEC) require public organizations to publish these documents regularly to ensure transparency and trust in global markets.
What are the types of financial statements?
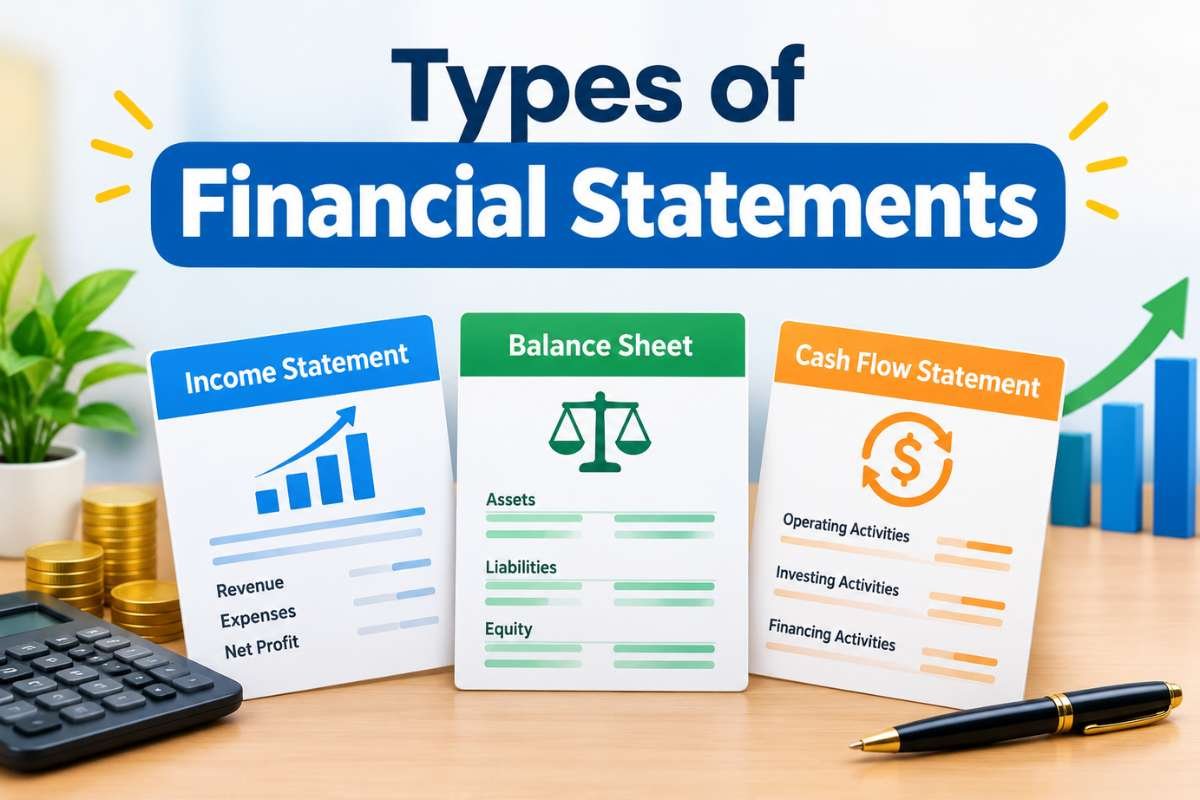
When financial professionals refer to the standard types of financial statements, they are describing the four fundamental accounting reports generated at the end of every reporting period (quarterly or annually):
- Income Statement (Profit & Loss)
- Balance Sheet (Statement of Financial Position)
- Statement of Cash Flows
- Statement of Stockholders’ Equity
These reports follow set accounting frameworks, such as Generally Accepted Accounting Principles (GAAP) in the United States or International Financial Reporting Standards (IFRS) internationally. Each statement serves a specific analytical function, but none tells the whole story on its own.
| INCOME STATEMENT (Net Income feeds into Equity) |
⇩
| STATEMENT OF OWNER’S EQUITY (Ending Equity feeds Balance Sheet) |
⇩
| BALANCE SHEET (Cash Balance links to Cash Flow) |
⇩
| CASH FLOW STATEMENT (Reconciles Cash across periods) |
The four standard types of financial statements
1. Income statement (profit and loss)
The Income Statement reports a business’s revenues, expenses, and net profit or loss over a specific period (e.g., Q1 or Fiscal Year 2025).
- Core Formula: 𝑅𝑒𝑣𝑒𝑛𝑢𝑒𝑠 − 𝐸𝑥𝑝𝑒𝑛𝑠𝑒𝑠 = 𝑁𝑒𝑡𝐼𝑛𝑐𝑜𝑚𝑒
- Key Components: Gross Revenue, Cost of Goods Sold (COGS), Operating Expenses (OPEX), Tax, and Net Income.
Real-World Example: In Apple Inc.’s FY2024 annual filing, Apple reported $391.04 billion in total net sales and $93.74 billion in net income. This shows that for every dollar generated, Apple retained over 23 cents in pure profit, illustrating high pricing power and strong operating efficiency.
2. Balance sheet
The Balance Sheet provides a snapshot of what a business owns (assets) and what it owes (liabilities), alongside the owners’ stake (equity) at a single point in time.
- Core Formula: 𝐴𝑠𝑠𝑒𝑡𝑠 = 𝐿𝑖𝑎𝑏𝑖𝑙𝑖𝑡𝑖𝑒𝑠 + 𝑆ℎ𝑎𝑟𝑒ℎ𝑜𝑙𝑑𝑒𝑟𝑠’𝐸𝑞𝑢𝑖𝑡𝑦
- Key Components: Current Assets (Cash, Accounts Receivable), Non-Current Assets (Equipment, Real Estate), Current Liabilities (Accounts Payable, Short-Term Debt), and Equity.
Real-World Example: In Microsoft’s Q4 FY2024 quarterly balance sheet, Microsoft reported $512.16 billion in total assets balanced against $243.69 billion in liabilities and $268.47 billion in total stockholders’ equity, demonstrating an incredibly strong capital cushion.
3. Cash flow statement
While the income statement accounts for revenues earned and expenses incurred (accrual accounting), the Cash Flow Statement tracks actual cash moving in and out of the business across three categories:
- Operating Activities: Cash generated or used in core day-to-day operations.
- Investing Activities: Cash spent on capital expenditures, property, plant, equipment, or acquisitions.
- Financing Activities: Cash raised from or paid to equity holders and debt providers (dividends, share buybacks, debt issuance).
Real-World Example: Tesla’s FY2023 financial reports showed $13.25 billion generated from operating activities. However, because Tesla invested $8.9 billion back into gigafactories and manufacturing equipment (investing cash flow), its net free cash flow remained balanced for heavy future expansion.
4. Statement of stockholders’ equity
The Statement of Stockholders’ Equity tracks changes in the owners’ equity account over a reporting period. It reconciles beginning equity to ending equity by factoring in:
- Net Income (added from the Income Statement)
- Dividends paid out to shareholders (subtracted)
- Share issuances or stock buybacks
How the financial statements connect
Understanding how these distinct financial statements interact is vital for financial modeling, corporate strategy, and fundamental analysis:
| Statement Connection | How They Link |
|---|---|
| Income Statement → Equity Statement | Net Income from the income statement is transferred into Retained Earnings within the Equity Statement. |
| Equity Statement → Balance Sheet | The Ending Stockholder’s Equity balance directly updates the equity section on the Balance Sheet. |
| Cash Flow → Balance Sheet | The Ending Cash Balance from the Cash Flow Statement must match the exact Cash & Cash Equivalents line item on the Balance Sheet. |
Who uses financial statements?
Different stakeholders analyze financial statements for distinct decision-making processes:
- Internal Management & Executives: To evaluate operational margins, allocate budgets, track department heads, and plan capital investments.
- Equity Investors & Venture Capitalists: To determine business valuation, calculate return on equity (ROE), and estimate growth potential.
- Lenders & Commercial Banks: To run solvency analysis, assess debt-service coverage ratios (DSCR), and set loan covenants.
- Tax Authorities (IRS) & Regulatory Bodies (SEC): To ensure compliance with tax codes and maintain fair, transparent public capital markets.
Conclusion
Understanding the four regular types of financial statements gives you the foundation to evaluate any business accurately.
By reviewing the income statement, balance sheet, cash flow statement, and statement of equity together, you gain a complete view of a company’s profitability, solvency, and operational performance.
FAQs on types of financial statements
1. What are the four main types of financial statements?
The four standard types of financial statements are the Income Statement, Balance Sheet, Cash Flow Statement, and Statement of Stockholders’ Equity.
2. Which financial statement is the most important?
No single financial statement tells the full story. The Income Statement shows profitability, the Balance Sheet reveals solvency and debt structure, and the Cash Flow Statement proves actual liquidity and solvency.
3. How do accrual accounting and cash flow differ?
Accrual accounting records revenues and expenses when they are earned or incurred, regardless of when money changes hands (reflected on the Income Statement). Cash flow tracks actual inflows and outflows of physical cash.
4. What is the primary accounting equation for the balance sheet?
The fundamental balance sheet equation is: Assets = Liabilities + Shareholders’ Equity. Both sides must always balance.
5. Why do investors focus heavily on the cash flow statement?
Investors prioritize cash flow because net income can be affected by non-cash accounting adjustments (like depreciation and amortization). Cash flow demonstrates whether a company generates real liquid cash to sustain operations and fund expansion.