Why finding the right health insurance plan matters
Navigating healthcare choices can feel overwhelming, but understanding the core types of health insurance plans is the fastest way to protect both your health and your wallet. Regular (or standard) managed care health plans govern how you access doctors, hospitals, and specialists, as well as how much you pay out-of-pocket for medical care.
According to the KFF Employer Health Benefits Survey, covered workers in the U.S. are spread across a few primary plan structures: Preferred Provider Organizations (PPOs) remain the most common, followed by High-Deductible Health Plans with Savings Options (HDHP/SO) and Health Maintenance Organizations (HMOs). Choosing among these structures dictates whether you need a referral to see a cardiologist, whether you can keep your primary care doctor, and whether you face unexpected medical bills.
Whether you are signing up during employer open enrollment or shopping on the Healthcare.gov marketplace, this comprehensive breakdown will guide you through each plan type, real-world examples, costs, and selection strategies.
The main types of health insurance plans
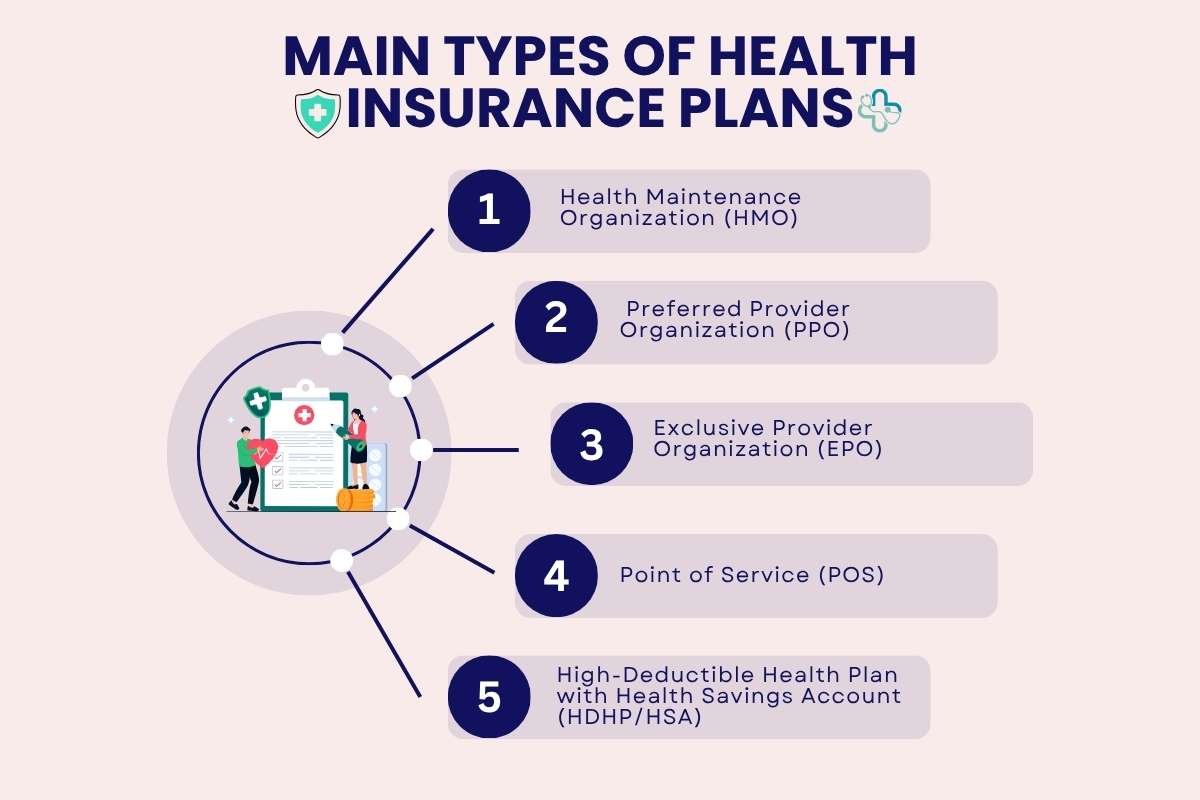
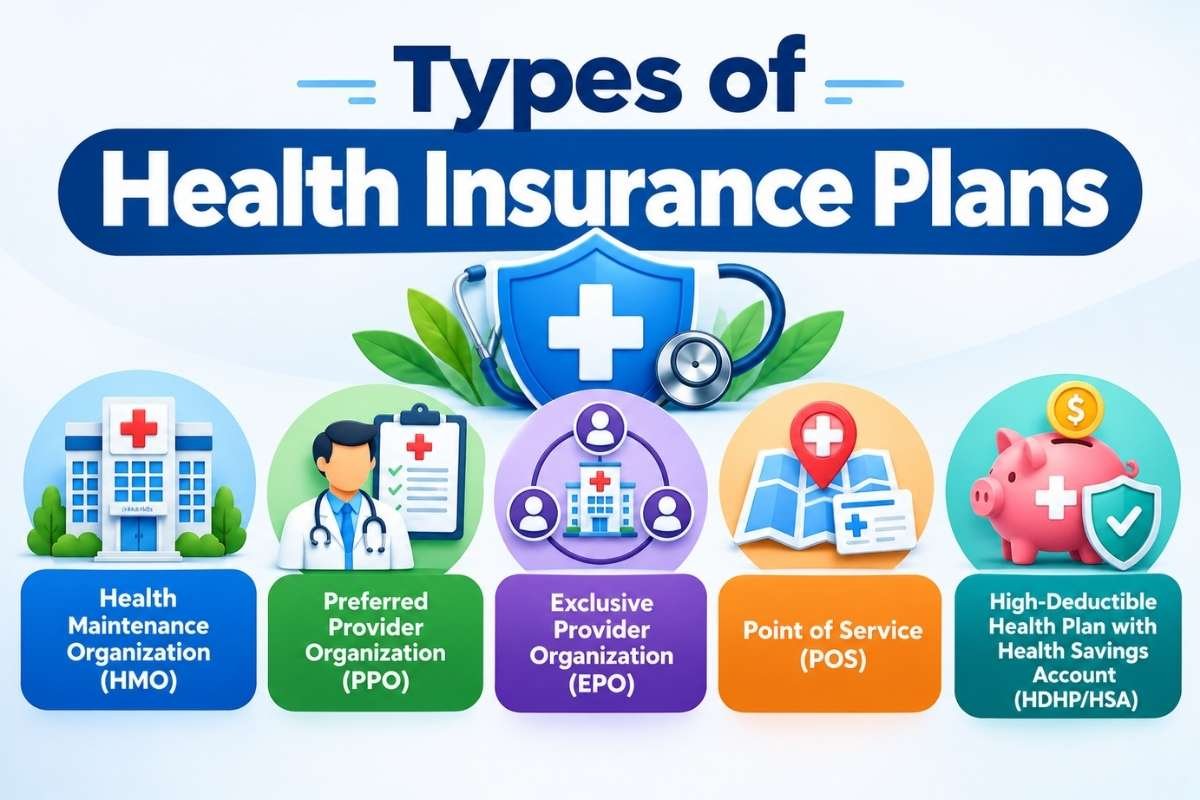
Managed care coverage generally falls into five primary categories. Here is how each health insurance structure functions in practice:
1. Health maintenance organization (HMO)
An HMO requires you to pick a Primary Care Physician (PCP) who coordinates all your healthcare services. To see a specialist, such as a dermatologist or gastroenterologist, you must first secure a referral from your PCP.
- Network Restrictions: HMOs strictly cover in-network care, except in genuine medical emergencies.
- Cost Structure: Low monthly premiums and predictable copays.
- Real-World Example: Kaiser Permanente operates one of the nation’s largest HMO models, integrating care delivery with coverage to keep administrative overhead low.
2. Preferred provider organization (PPO)
A PPO offers maximum freedom and flexibility. You do not need to select a primary care doctor, nor do you need referrals to visit specialists.
- Network Restrictions: You can receive care both in-network and out-of-network, though staying in-network incurs significantly lower out-of-pocket costs.
- Cost Structure: Higher monthly premiums and higher deductibles in exchange for scheduling independence.
- Real-World Example: Blue Cross Blue Shield provides extensive national PPO networks favored by remote workers and frequent travelers who require care across state lines.
3. Exclusive provider organization (EPO)
An EPO balances the flexibility of a PPO with the affordability of an HMO. Like a PPO, you rarely need a PCP referral to visit specialists. However, like an HMO, out-of-network care is not covered at all (except for emergencies).
- Network Restrictions: In-network doctors only.
- Cost Structure: Moderate premiums, usually lower than a PPO, with moderate deductibles.
- Real-World Example: Many employer plans offered through UnitedHealthcare use EPO network models to curb out-of-network spending while keeping specialist scheduling simple for policyholders.
4. Point of service (POS)
A POS plan combines features from both HMO and PPO frameworks. You must choose a Primary Care Physician who manages your referrals, but you retain the option to receive out-of-network care at a higher cost.
- Network Restrictions: Out-of-network coverage is available, but out-of-pocket costs and paperwork increase substantially outside the network.
- Cost Structure: Moderate premiums with variable out-of-pocket costs.
- Real-World Example: Cigna Health Care provides POS options for large employers whose workforce needs local care coordination alongside nationwide emergency and specialist access.
5. High-deductible health plan with health savings account (HDHP/HSA)
An HDHP features lower monthly premiums paired with a higher annual deductible. Per IRS standards, an HDHP can be combined with a tax-advantaged Health Savings Account (HSA), allowing you to pay for qualified medical expenses using pre-tax dollars.
- Network Restrictions: HDHPs can be structured as HMO, PPO, or EPO networks.
- Cost Structure: Low monthly premiums, high initial deductibles, and tax-deferred savings growth.
- Real-World Example: Health insurers like Aetna offer High-Deductible Health Plans (HDHPs) that may be paired with Health Savings Accounts (HSAs), which eligible individuals can use to save money for qualified medical expenses. HSA contributions and earnings may receive tax advantages under U.S. tax rules.
Direct side-by-side comparison of types of health insurance plans
| Plan Type | Requires Primary Doctor (PCP) | Requires Specialist Referrals? | Covers Out-of-Network Care? | Monthly Premium Level | Out-of-Pocket Expense Level |
|---|---|---|---|---|---|
| HMO | Yes | Yes | Emergency Only | Low | Low (Copays) |
| PPO | No | No | Yes (At higher cost) | High | Variable |
| EPO | No | No | Emergency Only | Moderate | Moderate |
| POS | Yes | Yes | Yes (With higher cost/paperwork) | Moderate | Moderate |
| HDHP/HSA | Depends on structure | Depends on structure | Depends on structure | Lowest | High upfront (until deductible) |
How to choose the right health insurance plan for your needs
Selecting among the various types of health insurance plans requires matching your expected medical usage with your financial situation:
- Assess Your Annual Care Needs: If you see multiple specialists or take brand-name medications regularly, a PPO prevents referral delays and ensures broad physician access. If you are generally healthy and only need annual checkups, an HDHP with an HSA lets you save on monthly premiums while building tax-free savings.
- Evaluate Your Network Flexibility: Check whether your existing doctors participate in the plan’s network before enrolling. According to consumer guides from the Centers for Medicare & Medicaid Services (CMS), using out-of-network providers in restrictive plans like HMOs or EPOs can lead to full balance billing for non-emergency services.
- Calculate Total Costs (Not Just Premiums): Add up your annual premium plus expected out-of-pocket costs (copays, coinsurance, and deductibles). A low-premium plan can prove more expensive overall if an unexpected illness forces you to hit a high deductible.
Conclusion
Understanding the different types of health insurance plans helps you choose coverage that fits your healthcare needs and budget. Whether you are enrolling in a new plan or changing jobs, compare your options carefully.
Consider factors such as provider networks, out-of-pocket costs, and access to specialists when choosing between HMO, PPO, EPO, POS, and HDHP plans. The right choice can help you manage healthcare expenses while getting the care you need.
FAQs on types of health insurance plans
1. What is the most common type of health insurance plan?
Preferred Provider Organizations (PPOs) remain the most popular managed care plans due to their broad networks and freedom to see specialists without primary care referrals.
2. Can I change my health insurance plan anytime?
Generally, no. You can change or enroll in a health plan during annual Open Enrollment or within 60 days of a Qualifying Life Event (such as marriage, job loss, or childbirth) under a Special Enrollment Period.
3. What is the primary difference between an HMO and an EPO?
Both HMOs and EPOs restrict coverage to in-network providers (except emergencies). However, HMOs require a primary care doctor and referrals for specialist visits, whereas EPOs allow you to book specialist appointments directly without a referral.